Chapter 2 - The Invoice That Didn’t Exist
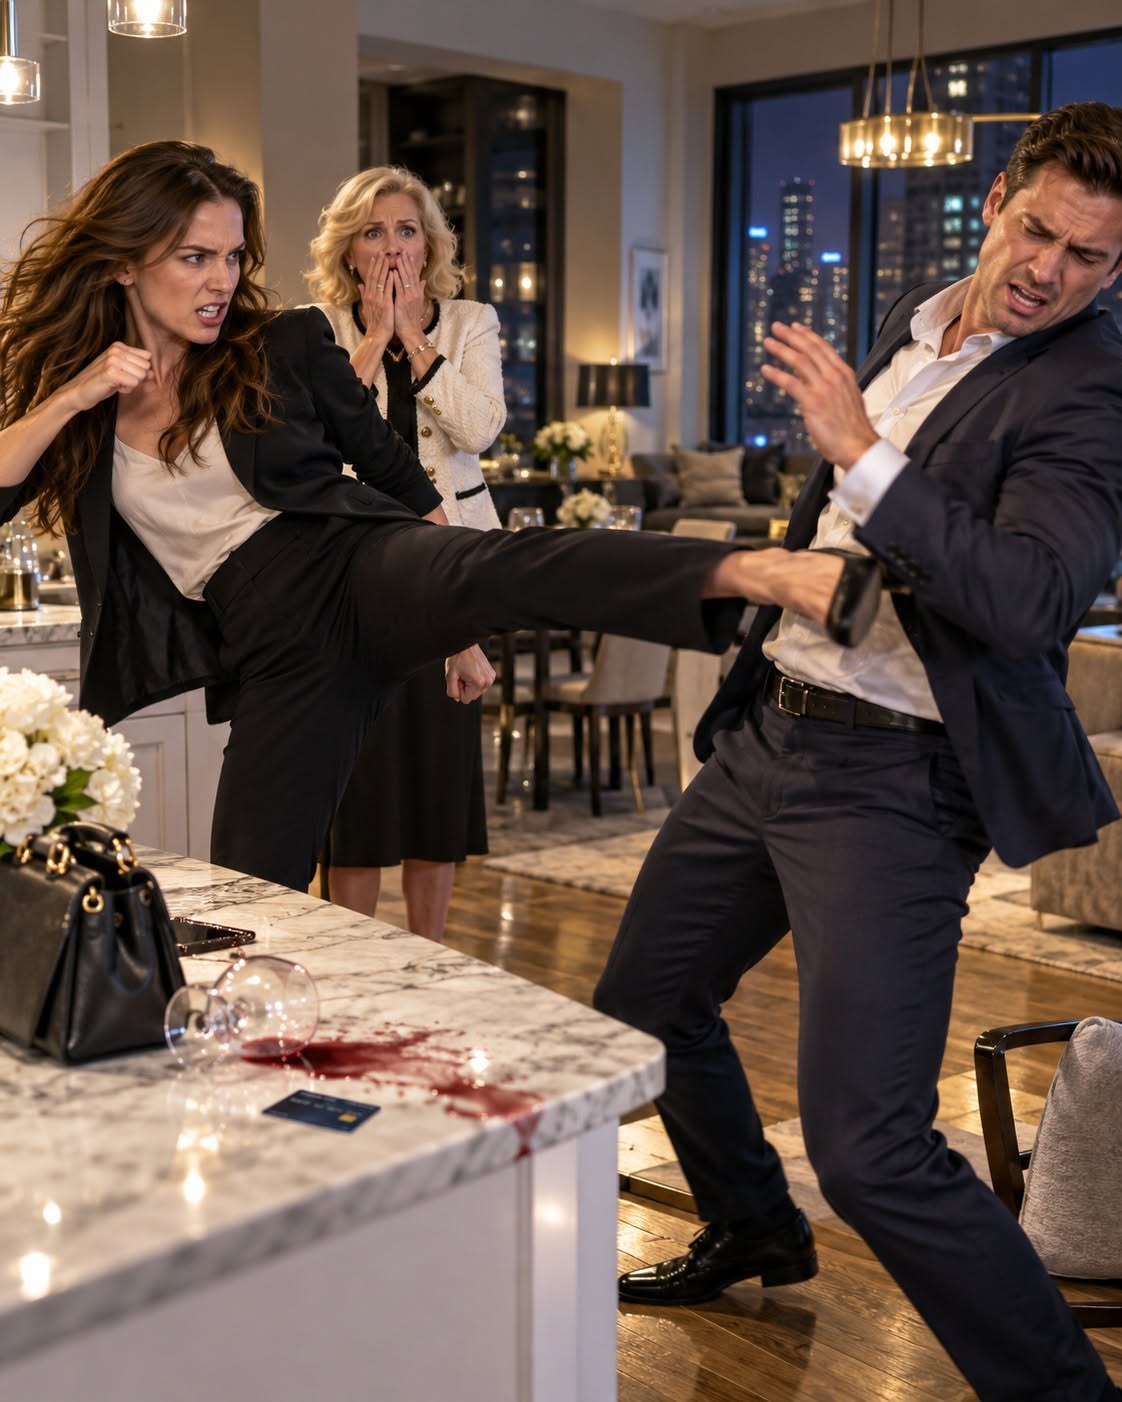
By midnight, my kitchen had become an evidence room.
I photographed every page of the ivory folder, created encrypted copies, and sealed the originals inside a document envelope. Then I called the one person who would understand why I could not wait until morning.
Naomi Brooks had been my closest friend since college and the attorney who helped establish my firm. She answered on the third ring.
“Whitney?”
“I need legal advice.”
“What happened?”
“My engagement ended.”
A pause followed. “Are you safe?”
“Yes.”
“Was anyone hurt?”
“No, but Chase blocked the door and raised his fist. I used enough force to get past him.”
“Call the police and document it.”
I hesitated.
That hesitation told Naomi more than my words had.
“Whitney,” she said, “you investigate people who rely on victims being too embarrassed to create a record. Don’t give Chase that advantage.”
I reported the incident. Two officers arrived, photographed the spilled wine and disordered chair, reviewed messages, and took my statement. I did not exaggerate. Chase had not struck me. I had kicked him once after he blocked my exit and raised his fist.
Building security provided footage showing Diane and Chase entering, then leaving twenty-seven minutes later. The hallway camera had no view of the kitchen, but it recorded Chase telling his mother, “She’s going to pay for this.”
By seven the next morning, Naomi sat across from me at the island with coffee and the documents.
She examined the forged signature.
“This is not amateur work,” she said.
“The invoices are.”
“Maybe because they didn’t expect you to see them.”
That was what disturbed me. Diane had expected me to surrender my card and PIN. The paperwork existed only to pressure me if I asked questions.
I called Bellweather Floral.
Their manager confirmed that our account was current. No emergency deposit existed.
Northstar Events had no record of our wedding.
“We’ve never worked with Mr. Mercer or Ms. Hayes,” the representative said.
The invoice was entirely fabricated.
At nine, Chase called from a number I did not recognize.
“I’m worried about you,” he said.
The tenderness in his voice was almost perfect.
“Why?”
“You had some kind of breakdown.”
“I had a boundary.”
“You kicked me.”
“You blocked my doorway and raised your fist.”
“I was gesturing.”
“You formed a fist.”
“You misread the situation.”
“Diane stole my card.”
“She picked it up.”
“And refused to return it.”
His voice hardened. “Are you recording this?”
“I’m documenting our communications.”
“That’s not normal.”
“Neither is forging my signature.”
Silence.
It lasted only two seconds, but it was the first honest thing he gave me.
“What are you talking about?” he asked.
“You left the folder.”
“My mother handles wedding paperwork.”
“The false invoices use a bank account connected to her.”
“You’re confused.”
“I’m canceling every wedding contract under my name. Do not contact my employees, clients, or family.”
“You can’t cancel everything. We have deposits.”
“I paid the deposits.”
“We made plans based on that wedding.”
The word plans caught my attention.
“What plans?”
He exhaled. “Our life, Whitney.”
“No. You said plans. Plural.”
“You’re interrogating me again.”
“I’m listening carefully.”
He ended the call.
By lunchtime, Diane had posted a vague statement online about “watching a beloved son endure abuse at the hands of a powerful woman.” She did not use my name, but she did not need to. Friends began messaging me.
Some asked whether I was safe.
Others asked what I had done to Chase.
One bridesmaid wrote, Diane says you attacked him because he questioned your spending.
I did not respond publicly. Naomi advised silence until we understood the scope of the fraud.
At my office, I told my business partner, Marcus Lee, that Chase and Diane were barred from the building. Marcus had joined the firm during its second year and could detect panic beneath my calm before most people noticed I was breathing differently.
“Personal problem or professional threat?” he asked.
“Both.”
We reviewed network access logs. Chase had never been given company credentials, but he had visited the office frequently. Twice, he had waited in my office while I finished meetings.
Marcus discovered an attempted login to our client portal from my condo’s network six months earlier. The username entered was mine. Three failed password attempts had triggered a silent security alert that our provider had classified as user error.
I had been attending a conference in Denver that day.
Chase had been alone in my condo.
The discovery felt more intimate than infidelity. He had not merely looked through a drawer. He had attempted to enter the system clients trusted me to protect.
We changed every password, invalidated all active sessions, and ordered a full forensic review.
Next, I examined Ivory Meridian.
Its account had received transfers from three companies associated with Chase’s real estate listings. The amounts were small enough to avoid casual scrutiny but large enough to sustain a lifestyle: $8,400, $12,750, $16,200.
I could not access private banking data, but public property records and civil filings revealed a pattern. Chase’s luxury career was collapsing. Two clients had sued him over missing escrow funds. One case had been settled confidentially. Another remained pending.
His sports car lease was four months behind before I paid it.
His apartment before moving into my condo had been subject to eviction proceedings.
The successful man I planned to marry had arrived in my life already drowning.
At four, an email appeared from Chase.
Subject: For Your Protection.
Attached was a draft statement prepared by an attorney. It said our confrontation resulted from my “acute work-related stress” and that I had “misinterpreted a loving family intervention.” If I signed, Chase would agree not to pursue charges for assault.
Naomi read it and laughed without humor.
“They want you to confess before he makes a formal accusation.”
At the bottom was an additional clause requiring both parties to keep “all shared financial arrangements” confidential.
“What shared arrangements?” I asked.
“That’s what they’re afraid you’ll discover.”
That evening, I searched my records at home.
Chase had encouraged me to go paperless, but I kept physical copies of important documents. My desk cabinet contained tax returns, company formation papers, insurance policies, and property records.
Nothing appeared missing.
Then I noticed a faint indentation in the carpet.
The small fireproof safe beneath my desk had been moved.
Inside, my documents looked orderly. Too orderly.
I checked the access history. The safe recorded every opening. My code had been used three times while I was away: once during the Denver conference, once during a client trip to New York, and once on a Saturday when Diane had taken me for a bridal fitting.
Chase knew the code because I had once asked him to retrieve my passport.
I changed it immediately.
Among my papers was a photocopy of a line-of-credit application I had never completed. The applicant was Hayes Forensic Accounting. The requested credit limit was $1.8 million.
The application listed my condo as collateral.
My forged signature appeared on the final page.
The broker was Mercer Premier Properties—Chase’s business.
A handwritten note in the margin read:
Activate immediately after marriage certificate records.
Beneath it were Diane’s initials.
Before I could call Naomi, my office security service contacted me.
A woman claiming to be my future mother-in-law had appeared downstairs with a locksmith and documents stating that Chase Mercer was a co-owner of Hayes Forensic Accounting.
The guard had refused them entry.
But Diane had left a copy of the document behind.
It was an operating agreement dated eleven months earlier.
According to it, I no longer owned my company alone.
May you like
Chase owned forty-nine percent.
And once again, the signature beside my name was a forgery.